Quick answer: underwriting workbench vs. traditional tools
An underwriting workbench replaces the fragmented mix of rating engines, Excel models, SharePoint guidelines, and email-based broker intake that defines "traditional underwriting tools" with a single application covering rules, AI risk scoring, document automation, and audit trail. The measurable gap is speed and consistency: rule deployment drops from 4-16 weeks to hours, and decision time on simple risks compresses from days to hours. Traditional tools still make sense for very low-volume specialty lines, carriers with unresolved data-quality problems, and books mid-cycle on a legacy contract, as the sections below explain.
Why this comparison matters for U.S. P&C carriers in 2026
Every modernization conversation I sit in on with carrier Boards starts with some version of the same question: how is an 'underwriting workbench' actually different from the underwriting tools we have been using for 15 years? The honest answer is that the term 'traditional underwriting tools' covers a range so wide that any single comparison is misleading without context. This article anchors that context.
From Excel + PAS screens to underwriting workbenches: what changed between 2020 and 2026
The traditional underwriting toolset for a mid-tier U.S. P&C carrier in 2020 typically included a rating engine bolted to the policy administration system, a separate guidelines repository in SharePoint or a shared drive, Excel models for complex risks, email-based broker submissions handled in Outlook, and a separate document management system for loss runs and schedules. Underwriters spent 60-70% of their day moving data between these systems.
Four shifts changed the picture between 2020 and 2026. Generative AI made document extraction production-grade for messy broker submissions, not just clean ACORD forms. The NAIC AI Model Bulletin moved AI governance from optional to enforced, with 24 states plus the District of Columbia having adopted it as of early 2026. No-code rules engines matured enough that CUOs author rules directly instead of filing IT tickets. And explainable AI techniques like SHAP and counterfactual explanations became a documented requirement under state-level rules such as New York's DFS Circular Letter No. 7, for any ML scoring that touches premium decisions in regulated markets.
Together these four shifts made the unified workbench architecture viable at mid-tier carrier scale. Before 2020, a workbench was a $30M+ enterprise project. After 2024, a $500M-$5B GWP carrier can deploy a partner-built workbench in 6-14 months for a fraction of that.
Underwriting workbench vs traditional tools: capability matrix
This is the comparison I draw on a whiteboard in carrier Board sessions. Note that 'traditional tools' here represents the median mid-tier P&C setup as of 2024, before the recent wave of generative AI integration.
Where traditional underwriting tools still hold up
I do not want to pretend traditional tools are universally inferior. They are not. From the carriers I have advised, there are at least three situations where traditional underwriting tools remain the better operational choice, at least for now.
Highly specialized lines with very low submission volume
If your line of business writes 200 risks a year at $500K+ average premium with extensive manual senior underwriter review on every submission, the workbench ROI math gets thin. A senior underwriter, a strong Excel rating model, and a good document repository can still outperform a workbench configuration that was not designed for that line.
Books where the data quality is the actual problem
If your loss data is 60% incomplete and your exposure data is inconsistent across legacy systems, a workbench will not fix that. It will surface it. I have seen two carriers spend $3M+ on workbench projects that stalled because data remediation should have come first. A workbench on top of bad data produces bad decisions faster.
Mid-cycle, late in a vendor contract
If you have 18 months left on a legacy underwriting platform contract with 7-figure exit fees, sometimes the right move is to extract maximum value from the current tools and build the workbench business case for the next contract cycle. Forcing a parallel deployment usually creates more risk than it removes.
Where the workbench advantage is measurable
Outside those three situations, the workbench advantage shows up in five anchor metrics from the deployments I have advised on. Loss ratio improves 3-5 points within 12-18 months as rule enforcement becomes consistent across all underwriters. Decision time on simple risks compresses from 4 days to 4 hours. Underwriter productivity rises 2-3x in policies per FTE. Quote-to-bind conversion improves 30-50% in the first 6 months after broker portal integration. And rule deployment time drops from 4 months to 24 hours, which is the speed-to-market lever that matters most to the CFO.
None of these are vendor-marketed numbers; they are what carriers report 12-18 months post-deployment. The variability across carriers is meaningful (a $750M GWP commercial lines carrier will see different numbers than a $3B GWP personal lines carrier), but the direction is consistent.
Modern underwriting workbench capabilities in 2026
Direct data flow from PAS to workbench
Modern workbenches layer on top of existing PAS infrastructure (Guidewire PolicyCenter, Duck Creek Policy, Majesco) rather than replacing it. Data flows bidirectionally through PAS APIs: submissions move from PAS to workbench for underwriting evaluation, decisions flow back to PAS for binding. The workbench owns underwriting decision logic and audit; the PAS owns policy of record.
Hybrid rules + ML risk assessment
Rules engines define hard eligibility and pricing guardrails. ML models score risks within those boundaries, surfacing patterns the rules cannot capture. Every score is logged with both the rule path and the model features that drove it, satisfying NAIC AI Bulletin documentation requirements while still capturing the ML upside.
Document automation for real submissions
OCR plus generative AI extraction now handles ACORD forms, loss runs in any carrier format, schedules of values in inconsistent Excel layouts, statement of values PDFs (scanned or native), and email threads with embedded context. The production test is your broker submission pile from last Tuesday, not the vendor's demo data.
Migration paths from traditional tools to a workbench
Three migration paths show up consistently in the modernization conversations I advise on. Full PAS replacement plus new workbench is the highest-risk and longest path (24-36 months) and rarely the right move for mid-tier carriers. Workbench layered on existing PAS is the most common (6-14 months) and lets carriers modernize underwriting without rebuilding policy of record. Phased rollout by line of business is the lowest-risk variant of the second path, taking one line live first and using lessons to compress timeline on subsequent lines.
For carriers running Guidewire, Duck Creek, or Majesco, the layered approach is almost always the right starting position. The integration patterns are covered in detail in our legacy systems integration article. The diagnostic for whether your carrier is ready is in our 5 signs piece. The full vendor feature checklist is in top features to look for.
And for the strategic framing of where underwriting is heading more broadly, the underwriting workbench guide is the pillar this article supports.
FAQ
What is an underwriting workbench compared to traditional underwriting tools?
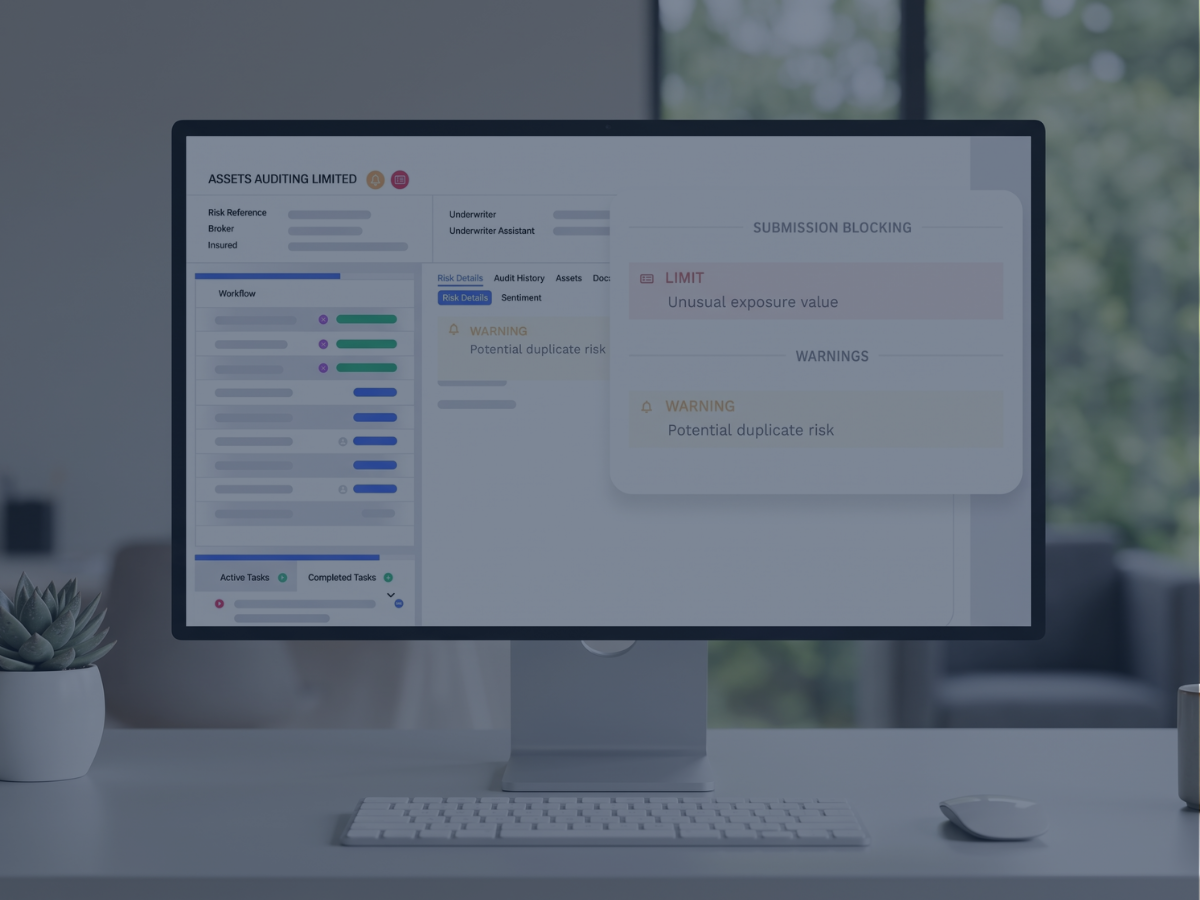
An underwriting workbench is a unified workspace that brings rules engine, AI risk scoring, document automation, broker portal, and audit trail into one screen for the underwriter. Traditional underwriting tools handle these functions across separate systems: a rating engine in PAS, guidelines in SharePoint, Excel models for complex risks, document management in a third system, and broker submissions in Outlook. The workbench compresses the underwriter workflow that spans 4-6 systems in traditional tools into a single application with one decision log.
What is the biggest measurable difference between workbench and traditional underwriting tools?
Rule deployment time is the single biggest measurable difference for mid-tier carriers. Traditional tools require 4-16 weeks to change a single eligibility or pricing rule because the change goes through IT backlog, regression testing, and a release window. Modern underwriting workbenches let the Chief Underwriting Officer or a delegated underwriter author the rule in a no-code interface, simulate the impact, and deploy in under 24 hours. This single capability drives the speed-to-market gap between mid-tier carriers running workbenches and those still on traditional tools.
Do traditional underwriting tools still make sense in 2026?
Yes, in three specific situations: highly specialized lines with very low submission volume where senior underwriter manual review is the right operational model; books where data quality is the bottleneck (a workbench surfaces bad data, it does not fix it); and the late stage of a multi-year legacy contract where exit fees outweigh workbench benefits. Outside these situations, the workbench advantage in loss ratio, decision time, and underwriter productivity is measurable enough to drive the business case for mid-tier P&C carriers in the $500M-$5B GWP range.
How does an underwriting workbench integrate with Guidewire or Duck Creek?
Modern workbenches layer on top of existing policy administration systems rather than replacing them. Higson, for example, has been deployed at carriers running Guidewire PolicyCenter, Duck Creek Policy, and Majesco, integrating through the PAS APIs without requiring PAS replacement. Submissions flow from PAS to workbench for evaluation; decisions flow back to PAS for binding. The workbench owns underwriting decision logic and audit trail; the PAS owns policy of record. This split lets mid-tier carriers modernize underwriting without a multi-year PAS rebuild.
What does the migration from traditional tools to a workbench actually look like?
The most common migration path for mid-tier carriers is workbench layered on existing PAS, taking 6-14 months from kickoff to first line of business in production. Phase 1 (months 1-3) is discovery, current-state mapping, and rule extraction from existing guidelines and Excel models. Phase 2 (months 4-8) is configuration, integration build, and rule authoring in the new system. Phase 3 (months 9-11) is UAT and parallel run against the legacy tools. Phase 4 (months 12-14) is phased cutover by line of business with optimization. Carriers that try big-bang cutover on multiple lines simultaneously consistently report higher post-deployment defect rates.
What underwriting workbench features matter most when replacing traditional tools?
Five features consistently separate workbenches that succeed in replacing traditional tools from those that fail post-deployment: CUO-controlled rules authoring (eliminates the IT backlog that traditional tools created), hybrid rules-plus-ML scoring with explainability built in (not bolted on), document automation that handles real broker submissions (not just clean ACORD demos), per-decision audit trail satisfying NAIC AI Bulletin requirements, and PAS-agnostic integration that does not force replacement of Guidewire, Duck Creek, or Majesco. The full evaluation checklist is in our top features article.
Talk to Decerto about Higson
If you are a Chief Underwriting Officer or VP Underwriting at a U.S. P&C carrier in the $500M-$5B GWP range, and your current underwriting workflow runs on a mix of PAS screens, Excel rating sheets, and email-based broker submissions, that is the exact pattern Higson was built to address. Higson layers on top of Guidewire PolicyCenter, Duck Creek Policy, or Majesco without forcing a PAS replacement, and ships a CUO-controlled rules engine that cuts rule deployment from a 4-month IT backlog to 24 hours.
My take, after 20 years on the carrier side: Higson is not the right fit for $5B+ enterprise carriers running multi-region multi-currency books across 30+ jurisdictions. Guidewire is. Higson is built for U.S. P&C carriers in the $500M-$5B GWP range that need rules-engine control and audit-grade documentation without a 24-month PAS replacement.
Sources
- National Association of Insurance Commissioners (NAIC). (2023, December 4). Model Bulletin: Use of Artificial Intelligence Systems by Insurers.
- National Association of Insurance Commissioners (NAIC). (2026, April). Implementation of NAIC Model Bulletin: Use of Artificial Intelligence Systems by Insurers (state adoption tracker).
- New York State Department of Financial Services (NY DFS). (2024, July 11). Insurance Circular Letter No. 7 (2024): Use of Artificial Intelligence Systems and External Consumer Data and Information Sources in Insurance Underwriting and Pricing.

Subscribe to receive the latest blog posts to your inbox every week.