Why CUOs are asking this question more in 2026
Three of the last five underwriting workbench deployments I advised on failed not because the workbench was wrong, but because the carrier missed the signs that a workbench was needed in the first place. They bought when their portfolio had already deteriorated, their senior underwriters had already retired, or their state DOI had already flagged inconsistent decisions. The signs below are the early-warning indicators I tell CUOs and Boards to act on before the audit letter arrives.
Sign 1: Decision time on simple risks measured in days, not hours
On a routine personal auto risk or a clean small commercial submission, the time from submission intake to bind decision should be measured in hours, not days. In modern underwriting workbenches with straight-through processing for low-complexity risks, the median is closer to 4 hours. In carriers running traditional tools (Excel rating sheets, email-based submissions, manual document re-keying), the median is closer to 4 days, and the 90th percentile is often 2 weeks.
The operational cost is double. First, brokers route business to faster carriers when quote turnaround is slow: quote-to-bind conversion typically improves 30-50% in the first 6 months after a workbench deployment compresses decision time. Second, senior underwriter capacity is wasted on routine cases that AI plus rules could handle, leaving less time for complex risks where their judgment actually matters.
The diagnostic question: pull your last 100 personal auto submissions. What was the median time from broker submission to quote? If it is more than 24 hours, you are losing business to faster competitors and overusing senior underwriter capacity.
Sign 2: Underwriters apply 'the same' rule in materially different ways
This is the sign that hits hardest in Board sessions. I have seen carriers where 12 underwriters applied the same guideline 47 different ways on a sample of 200 submissions, all believing they were following the rule. The guideline existed in a Word document and a SharePoint folder. Without rule enforcement in a centralized engine, the 'rule' is whatever each underwriter remembers it to be.
The financial impact shows up in loss ratio drift. When rules are enforced inconsistently, adverse selection patterns slip through guideline exceptions that some underwriters accept and others decline. Loss ratio degrades 2-4 points over 18-24 months before the pattern is visible in standard reporting. Modern workbenches with centralized rules engines typically improve loss ratio 3-5 points within 12-18 months of deployment, partly by closing this consistency gap.
The diagnostic question: take one specific underwriting guideline (say, the rule for homeowners with roof age greater than 15 years) and ask three underwriters how they apply it. If you get three meaningfully different answers, the rule does not exist as an enforced rule; it exists as a suggestion.
Sign 3: Rule changes take 4-16 weeks because everything routes through IT
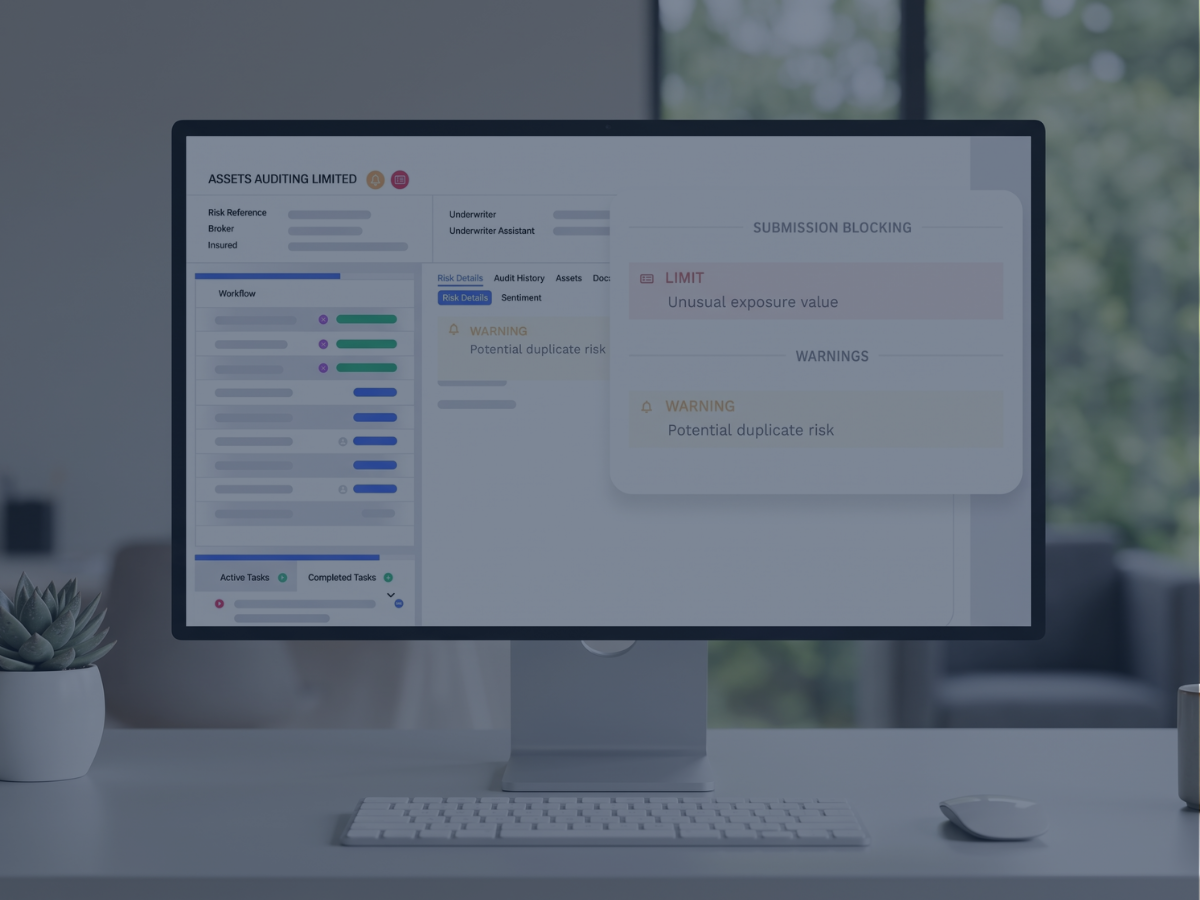
When the CUO needs to tighten an eligibility rule because loss data shows a new pattern, the time-to-deploy that rule change is the single best predictor of carrier competitiveness in 2026. In carriers running traditional tools (rating engines bolted to PAS, rules embedded in PAS configuration, IT-managed deployment cycles), rule changes take 4-16 weeks. JIRA tickets, regression testing, release windows, stakeholder reviews. In carriers with modern workbenches, the CUO or a delegated underwriter authors the rule in a no-code interface, simulates impact against the back-book, and deploys in under 24 hours.
The competitive impact is meaningful. Specialty carriers and MGAs that launch new products in 8-12 weeks have rules-engine flexibility that lets them iterate weekly based on market feedback. Incumbent carriers with 4-month rule deployment cycles cannot match that iteration speed. Boards have stopped accepting 'IT backlog' as an explanation for slow product launches.
The diagnostic question: how long did it take to deploy your last 3 underwriting rule changes from CUO decision to production effect? If the answer is more than 2 weeks, you are operating on a 2015 deployment cycle in a 2026 market.
Sign 4: You cannot answer NAIC AI Bulletin documentation questions on demand
The NAIC AI Model Bulletin, adopted by 24 states plus the District of Columbia as of April 2026, requires carriers using AI in underwriting to produce five artifacts on regulator request: written AI Systems Program documentation, model card, validation report, bias testing summary, and per-decision audit trail. The NAIC AI Systems Evaluation Tool pilot in 12 states (California, Colorado, Connecticut, Florida, Iowa, Louisiana, Maryland, Pennsylvania, Rhode Island, Vermont, Virginia, and Wisconsin) is running from March through September 2026 and is actively examining these artifacts.
If your underwriting team uses any ML scoring today (third-party fraud scoring, internal risk models, vendor-provided predictive analytics) and you cannot produce those five artifacts within 30 days of a regulator request, you are exposed. From the compliance retrofits I have seen, building those artifacts after a regulator request costs 18-36 months and seven-figure budgets. Building them in as part of a workbench deployment is materially cheaper.
The diagnostic question: ask your compliance officer to produce a model card and validation report for the most recent AI scoring model your underwriting team uses. If the answer is 'we will need to build that,' you have a sign 4 exposure.
Sign 5: Senior underwriters are retiring with institutional knowledge in their heads
The 25-year senior underwriter who knows which broker is reliable, which combination of exposures predicts adverse selection, which guideline exceptions historically work and which do not: that institutional knowledge is the most valuable asset on the underwriting team and the least documented. The carriers I have advised are losing 10-20% of senior underwriting headcount per year to retirement, and most of that knowledge is not written down anywhere.
Modern underwriting workbenches are increasingly the mechanism for codifying that knowledge before it walks out the door. The senior underwriter's rules of thumb become rules in the engine. Their pattern recognition becomes ML model features. Their broker knowledge becomes broker performance scoring. Once codified, the knowledge does not retire.
The diagnostic question: of your senior underwriters with 20+ years of experience, what percentage will retire in the next 5 years, and what specifically have you captured of their decision logic? If the first number is over 30% and the second answer is 'not much,' you have a sign 5 exposure that will hit loss ratio harder than any of the previous four.
Self-assessment matrix: where does your carrier score?
Score each of the five signs on a 0-2 scale, then total. This is the diagnostic I run with carrier Boards in modernization conversations.
Total 0-3: Healthy. Your underwriting operation is keeping pace with 2026 standards. Continue monitoring; revisit annually. Total 4-6: Plan upgrade. You have material gaps that will hit loss ratio, audit position, or competitive speed within 12-24 months. Begin workbench evaluation now to be in production by 2027. Total 7-10: Urgent. You are losing capacity, exposed to regulatory examination, and likely losing senior underwriter knowledge faster than you can recover. Workbench deployment should be a current-year Board priority.
What happens after you identify the signs
From the carriers I have advised through this diagnostic, three patterns separate carriers who move fast and well from carriers who stall.
First, scope by line of business, not by capability. Take your highest-volume line (often personal auto or small commercial) and design the workbench deployment around it. Add specialty and complex lines in later phases. Carriers that tried to deploy across all lines simultaneously consistently reported higher post-deployment defect rates.
Second, address data quality before workbench cutover, not after. A workbench on top of bad data produces bad decisions faster, not better decisions. The carriers that succeeded invested 3-6 months in data remediation before any workbench configuration.
Third, treat the workbench as the codification mechanism for senior underwriter knowledge, not just the new decision system. The carriers that paired workbench deployment with explicit knowledge-capture workshops (where senior underwriters work with rule authors to encode their decision logic) captured 5-10x more institutional knowledge than carriers that treated the workbench as IT delivery.
For the foundational view of what an underwriting workbench is and what it includes, see our underwriting workbench guide. For the detailed feature checklist when selecting a vendor, see top features to look for. For the comparison between workbenches and traditional tools, see workbench vs traditional tools. And for the senior-underwriter knowledge codification angle specifically, see will AI replace underwriters.
FAQ
What are the signs that a P&C carrier needs an advanced underwriting workbench in 2026?
Five operational signs consistently indicate workbench need for U.S. P&C carriers in the $500M-$5B GWP range: decision time on simple risks measured in days rather than hours; underwriters applying 'the same' rule in materially different ways across the team; rule changes taking 4-16 weeks because they route through IT; inability to produce NAIC AI Bulletin documentation on regulator demand; and senior underwriters retiring with institutional knowledge that lives only in their heads. Two or more active signs typically indicate the carrier is losing capacity, decision quality, or audit position.
How long does it take to deploy an underwriting workbench at a mid-tier carrier?
Typical deployment timeline for a mid-tier P&C carrier in the $500M-$5B GWP range is 6-14 months for a partner-led workbench on existing PAS, covering one line of business from kickoff to production. The phases are discovery and rule extraction (months 1-3), configuration and integration build (months 4-8), UAT and parallel run against legacy tools (months 9-11), and phased cutover with optimization (months 12-14). Off-the-shelf vendor implementations run 12-24 months in practice. Custom builds run 24-36 months and require sustained engineering depth that mid-tier carriers rarely have.
What is the cost of waiting to deploy an underwriting workbench in 2026?
The cost of waiting compounds across four areas. Loss ratio degrades 2-4 points over 18-24 months when rules are applied inconsistently across the underwriting team. Quote-to-bind conversion drops as brokers route business to faster competitors. NAIC AI Bulletin compliance retrofit costs 18-36 months and seven-figure budgets when addressed reactively after a regulator request. Senior underwriter retirements take institutional knowledge that cannot be reconstructed once it is gone. From the carriers I have advised, the 12-18 month cost of waiting typically exceeds the cost of a workbench deployment.
Do all underwriting workbenches solve the same problems?
No. Workbenches vary significantly in capability across rules-engine flexibility, AI scoring depth, document automation accuracy on real broker submissions, PAS integration patterns, and NAIC AI Bulletin compliance posture. For mid-tier P&C carriers, the five capabilities that consistently separate production-grade workbenches from lighter offerings are CUO-controlled rules authoring, hybrid rules-plus-ML scoring with explainability, document automation for unstructured submissions, per-decision audit trail, and PAS-agnostic integration (works with Guidewire, Duck Creek, or Majesco without forcing replacement). The full feature checklist is in our top features to look for article.
How does a carrier build the business case for an underwriting workbench in 2026?
The business case rests on five anchor metrics from real deployments: 3-5 points of loss ratio improvement within 12-18 months as rule consistency tightens; decision time on simple risks compressing from 4 days to 4 hours, with corresponding broker conversion gains of 30-50% in the first 6 months; underwriter productivity rising 2-3x in policies per FTE; rule deployment time dropping from 4 months to 24 hours, supporting faster product launches; and NAIC AI Bulletin compliance built in rather than retrofitted at multi-million-dollar cost. The financial case for a $1B GWP carrier typically shows payback in 14-22 months from a $2M-$5M workbench investment.
Should the CIO or the CUO own the underwriting workbench decision?
The CUO owns the decision; the CIO owns the deployment. From the carrier Boards I advise, the deployments that succeeded had the Chief Underwriting Officer or VP Underwriting as the named owner of the business case, rule logic, and post-deployment outcomes. The CIO and IT team owned PAS integration, infrastructure, and data migration. Deployments that flipped this (CIO-led with underwriting as a stakeholder) consistently produced workbenches that satisfied technical requirements but missed underwriting workflow needs, requiring 6-12 months of post-deployment remediation.
Talk to Decerto about Higson
If you are a Chief Underwriting Officer or VP Underwriting at a U.S. P&C carrier in the $500M-$5B GWP range, and your current underwriting workflow runs on a mix of PAS screens, Excel rating sheets, and email-based broker submissions, that is the exact pattern Higson was built to address. Higson layers on top of Guidewire PolicyCenter, Duck Creek Policy, or Majesco without forcing a PAS replacement, and ships a CUO-controlled rules engine that cuts rule deployment from a 4-month IT backlog to 24 hours.
My take, after 20 years on the carrier side: Higson is not the right fit for $5B+ enterprise carriers running multi-region multi-currency books across 30+ jurisdictions. Guidewire is. Higson is built for U.S. P&C carriers in the $500M-$5B GWP range that need rules-engine control and audit-grade documentation without a 24-month PAS replacement.
Sources
- National Association of Insurance Commissioners (NAIC 2023, December 4).
- NAIC Innovation, Cybersecurity, and Technology (H) Committee (2026, April 1, status date).
- NAIC Big Data and Artificial Intelligence (H) Working Group (2026).

Subscribe to receive the latest blog posts to your inbox every week.